Blog / Chevrolet Financing Central Florida

Where Can I Get a Chevy Silverado Loan With Low APR Near The Villages?

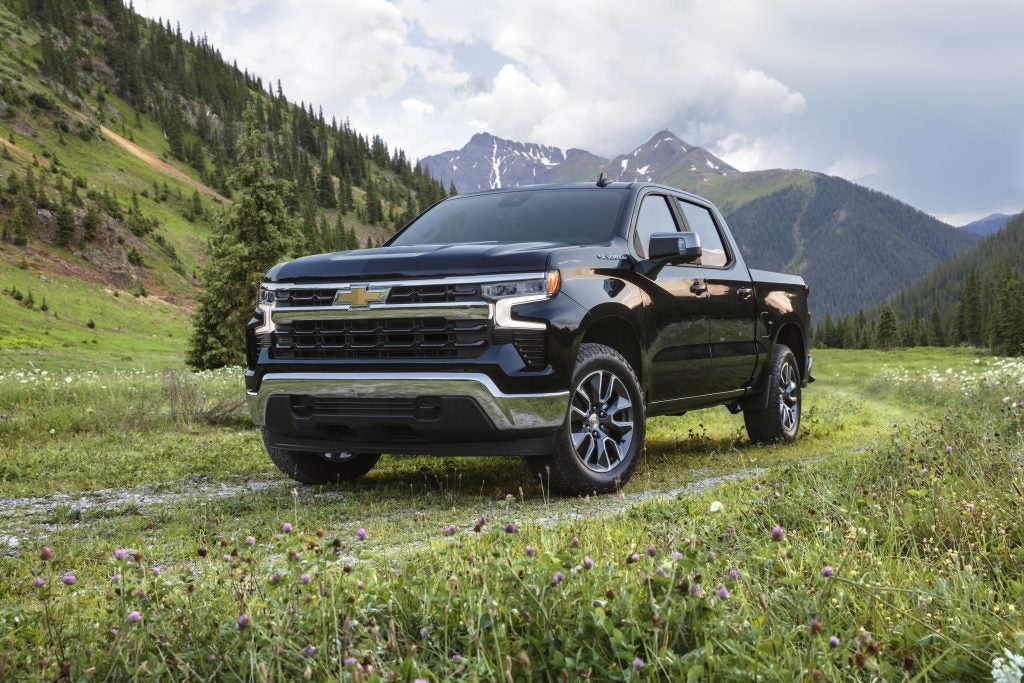
Black Chevrolet Silverado pickup, the truck Villages-area buyers compare low-APR loan offers on at Cecil Clark Chevrolet

The lowest APR on a Chevy Silverado loan near The Villages usually comes from a GM Financial promotional rate offered through a Chevrolet dealer, and three things decide whether you get it: your credit tier, your loan term and whether you take the special APR instead of a cash-back offer. At Cecil Clark Chevrolet in Leesburg, a short drive down US HWY 441, we put every current Silverado financing path side by side so you can see which one costs less over the life of the loan — the same approach behind our guide to Chevrolet financing options across Central Florida. Rates change every month, so this page explains how the numbers are set rather than quoting a figure that will be out of date by the time you read it.

Quick answer: how to get a low-APR Silverado loan near The Villages

Ask for GM Financial's current special APR on the exact Silverado model year and trim you want. The advertised rate goes to buyers in the top credit tiers. Shorter terms usually carry the lowest rates. Compare the special APR against the cash-back offer, because many months you cannot have both. Get pre-qualified first so you know where you stand.

Get Pre-Qualified for a Silverado Loan

How Your Silverado APR Gets Set

A Silverado APR is not one number on a sign. The advertised special rate is the best case, and the rate that ends up on your contract comes from four inputs a lender weighs every time someone finances a new truck. Knowing them before you sit down is the simplest way to avoid paying more interest than you need to.

Your Credit Tier

GM Financial sorts applicants into credit tiers, and advertised special rates are reserved for well-qualified buyers in the top tiers. Lower tiers can still be approved, usually at a higher rate.

The Loan Term

Special APR offers are tied to specific terms. The lowest rate usually applies to a shorter loan, while the longest terms carry a higher promotional rate or none at all.

Special APR vs. Cash Back

Chevrolet often offers either a reduced rate or a cash allowance on a Silverado. Some offers combine and many do not, so the fine print decides which deal you are really choosing between.

Model Year and Trim

Offers change by model year and trim. A Silverado 1500 and a Silverado HD on the same lot can carry very different financing offers in the same month.

Ways to Finance a Silverado at a Low Rate Near The Villages

GM Financial Special APR — Lowest Advertised Rate

Promotional financing through GM Financial, available only through Chevrolet dealers. It is the strongest option for well-qualified buyers who plan to keep the truck for most or all of the loan term.

Cash Back Plus Standard Financing — Lower Price Up Front

Taking a cash allowance lowers the amount you borrow. If you expect to pay the truck off early or put a large amount down, the rebate can save more than a reduced rate would.

Credit Union or Bank Pre-Approval — Best Benchmark

A pre-approval from your own bank or credit union gives you a rate to measure the dealer's offer against. Bring it with you; if the promotional rate is lower, you simply use that instead.

Shorter Loan Term — Least Interest Paid

A shorter term raises the monthly payment but usually earns the lowest promotional rate and cuts total interest. Stretching to the longest term lowers the payment while costing more over time.

Outgoing Model Year — Often the Richest Offers

When a new model year arrives, the remaining trucks from the previous year often carry larger incentives. Ask which model years are on the lot and what each one is offering this month.
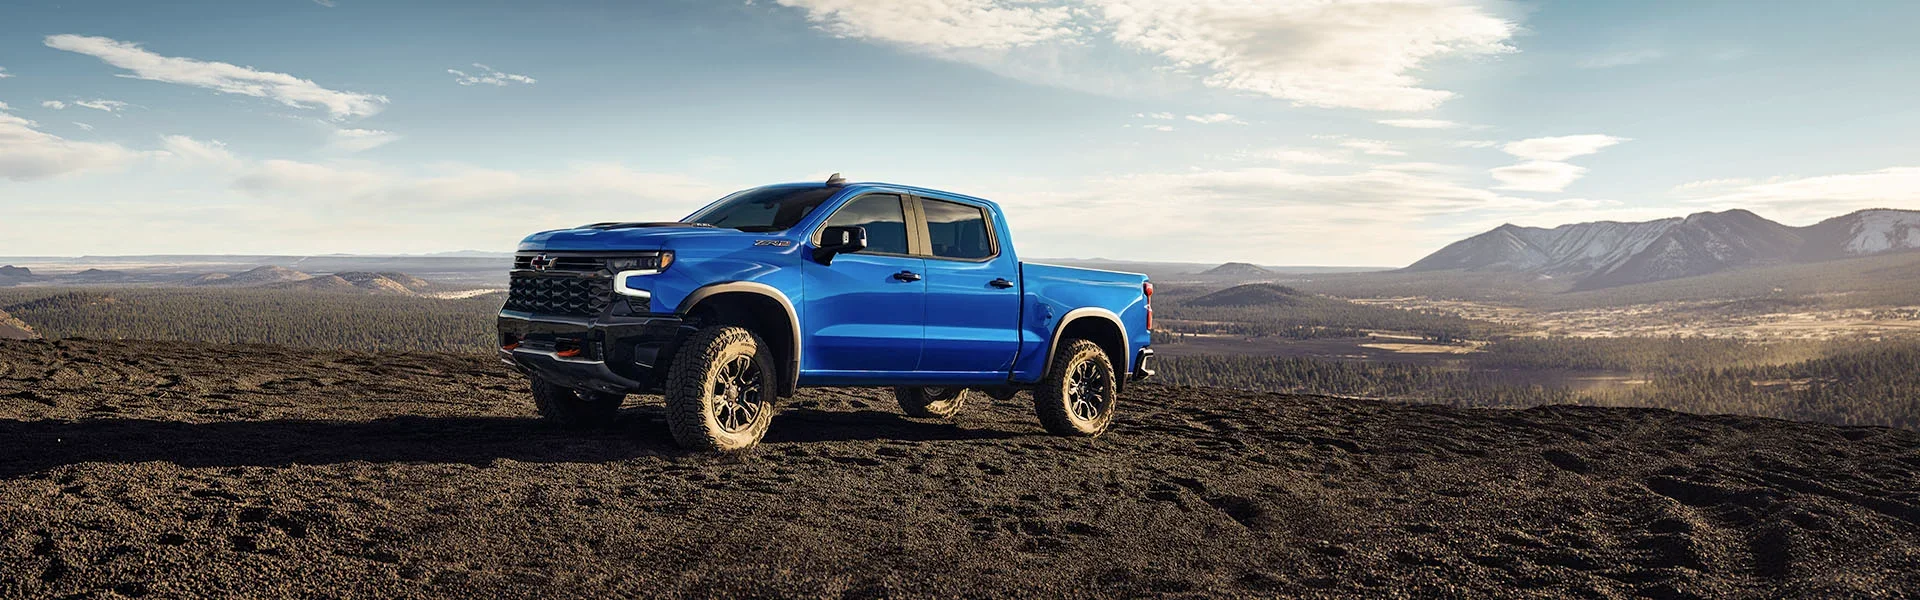
Blue Chevrolet Silverado 1500 pickup, one of the trucks Villages-area buyers finance through GM Financial at Cecil Clark Chevrolet

See This Month's Silverado Offers

Special APR or Cash Back: How to Compare the Two

The cleanest comparison is total cost, not the monthly payment. Start with the truck's price after any discounts you qualify for. For the special-APR path, keep only the cash offers that are allowed to combine with it and figure the payment at the promotional rate. For the cash-back path, subtract the rebate and figure the payment at the rate you would get from GM Financial's standard program or your own lender. Multiply each payment by the number of months, add your down payment, and the lower total wins. Every GM Financial offer also lists the monthly payment for each $1,000 financed, which makes two terms easy to compare at a glance. Monthly offers work the same way on the lease side, which we walk through in our look at this month's Chevy Equinox lease deals near Tavares.

Can You Deduct the Interest on a Silverado Loan?

Possibly. The federal car loan interest deduction, which runs from 2025 through 2028, lets you deduct up to $10,000 a year in interest on a loan for a new vehicle bought for personal use, as long as the loan started after December 31, 2024, the vehicle's gross vehicle weight rating is under 14,000 pounds and it went through final assembly in the United States. That last rule is where Silverados differ: GM builds them at more than one plant, and not every plant is in the U.S., so two trucks on the same lot can have different answers. Check the final assembly location on the truck's vehicle information label, or run its VIN through NHTSA's VIN decoder, which shows the build plant and country. The deduction phases out above $100,000 of modified adjusted gross income, or $200,000 for joint filers, and the IRS explanation of the car loan interest deduction covers the rest. A tax professional can tell you how it applies to your return.

Serving Silverado buyers across The Villages and Lake County

We finance, deliver and service Silverados for drivers in The Villages, Lady Lake, Fruitland Park, Leesburg and the rest of Lake County. Free local delivery on new and pre-owned purchases reaches anywhere within 50 miles of the store, which covers all of The Villages.

Compare Silverado Loan Payments

Frequently Asked Questions

Where can I get a low APR loan on a Chevy Silverado near The Villages?

The lowest Silverado rates near The Villages usually come from GM Financial's special APR offers, which are available through Chevrolet dealers such as Cecil Clark Chevrolet on US HWY 441 in Leesburg. Those rates go to well-qualified buyers on specific loan terms and change every month, so ask for the current offer on the exact model year and trim, and compare it with a bank or credit union pre-approval.

Who qualifies for GM Financial's special APR on a Silverado?

GM Financial's advertised special APR is reserved for well-qualified buyers, which generally means applicants in its top credit tiers. Approval and the final rate also depend on the loan term, the amount financed and the specific offer that month. If you land in a lower tier, you can still finance a Silverado, but your rate will typically be higher than the advertised promotional rate.

Should I take the special APR or the cash back on a new Silverado?

Compare total cost rather than the monthly payment. Run one payment using the special APR and another using the cash-back price at a standard rate, then multiply each payment by the number of months. If you plan to keep the loan for the full term, the special APR often wins. If you will pay the truck off early or put a lot down, cash back can come out ahead.

Can I deduct the interest on my Silverado loan from my taxes?

You may be able to. From 2025 through 2028, federal law allows a deduction of up to $10,000 a year in interest on a loan taken out after 2024 for a new personal-use vehicle that went through final assembly in the United States. Silverados are built at more than one plant, so eligibility depends on the specific truck. Check its vehicle information label or VIN, and confirm with a tax professional.

Can I get pre-qualified for a Silverado loan before I visit the dealership?

Yes. Cecil Clark Chevrolet has an online pre-qualification form you can complete before you visit, so you arrive with a clearer picture of your financing options. If you have a pre-approval from your own bank or credit union, bring that too. Having both lets the finance team compare GM Financial's current Silverado offer against your outside rate on the spot and choose whichever costs less.

Compare Silverado Loan Offers Near The Villages

Bring your pre-approval, your trade-in details and the Silverado you have in mind, and we will lay every current offer side by side so you can pick the lowest total cost. Family-owned and right on US HWY 441 in Leesburg since 1972.
Posted in:

Related Posts

Chevrolet auto loan financing paperwork being signed at Cecil Clark Chevrolet in Leesburg, FL

Chevrolet Auto Loans for Bad Credit Near Leesburg, FL

Yes — you can get approved for a Chevrolet auto loan in Leesburg, FL even with bad credit. At Cecil Clark Chevrolet, our finance team works with a broad network of lenders who evaluate applications individually rather than relying on a single credit score cutoff. We've helped buyers across a wide range of credit situations, from first-time buyers with no credit history to customers rebuilding credit after a past financial setback. We're located at 8843 US HWY 441 in Leesburg, just a short drive from The Villages, and you can start the process from home by getting pre-qualified online before you ever visit. We work with buyers throughout Leesburg, The Villages, Lady Lake, Eustis, Wildwood and the rest of Sumter and Lake County who need financing help that goes beyond a simple credit-score checkbox. Getting approved with bad credit is common, and our finance team has helped many local buyers do exactly that. Get Pre-Qualified Now How Bad Credit Auto Loan Approval Works Near Leesburg Bad credit doesn't have to mean no financing. Here's how our process works for buyers who are worried their credit score will hold them back: Multiple lending partners — we submit your application to a network of lenders, not just one bank, which improves your odds of approval and better terms. Individual application review — our finance team looks at your full financial picture, including income and employment history, not just a single credit number. Online pre-qualification — get a sense of your options from home before you ever step into the dealership. Trade-in and down payment flexibility — a trade-in or down payment can improve your terms even with a lower credit score. Start Your Pre-Qualification Know Your Buying Power Before You Shop Our What's My Buying Power tool gives you a realistic sense of your budget before you start shopping, so you're not guessing at what you can afford. Combined with pre-qualification, this helps take the anxiety out of financing conversations — you'll walk into our Finance Department already knowing roughly where you stand. Check My Buying Power Visit Our Finance Department Trading In Your Current Vehicle Can Help Even if your current vehicle has a loan balance remaining, a trade-in can lower the amount you need to finance and may help your approval terms. We give every trade-in a fast, fair estimate as part of the financing conversation so you understand exactly how it affects your deal before you sign anything. Get My Trade-In Value Vehicles That Fit a Rebuilding Budget If you're rebuilding credit or starting with a smaller down payment, our used vehicles under $19,995 and pre-owned specials are a great place to start. Our finance team can help match you to a vehicle that fits both your budget and your approval odds, rather than steering you toward something you can't comfortably afford. Shop Vehicles Under $19,995 View Pre-Owned Specials Why Leesburg-Area Buyers Trust Us with Their Financing A Network of Lending Partners We're not limited to one bank's approval criteria — we shop your application across multiple lenders to find the best fit for your situation. No-Pressure Conversations Our finance team explains your options clearly and answers questions honestly, so you understand every term before you sign. Family-Owned Since 1972 We've built long-term relationships with Central Florida customers for over 50 years, including many who started with us while rebuilding credit. Convenient to The Villages Our Leesburg showroom on US HWY 441 is a short drive from The Villages, Lady Lake and Wildwood. Learn More About Our Finance Department Frequently Asked Questions: Bad Credit Auto Loans Can I get approved for a Chevrolet auto loan in Leesburg, FL with bad credit? Yes. We work with a network of lenders that offer financing options for buyers with bad credit, limited credit history, or past bankruptcy. Our finance team reviews each application individually, and you can start the process by getting pre-qualified online before you visit. What credit score do I need to buy a Chevrolet at Cecil Clark Chevrolet? There is no single minimum credit score, because our finance team works with multiple lenders who each evaluate applications differently. We've helped buyers across a wide range of credit profiles, including first-time buyers and customers rebuilding credit. How do I get pre-qualified for financing before visiting the dealership? Complete our secure online pre-qualification form at cecilclarkchevrolet.com/get-pre-qualified-now.html. It takes just a few minutes and gives you a clearer picture of your options before you come in. Does a trade-in help if I have bad credit? Yes. A trade-in, even one with a remaining loan balance, can reduce the amount you need to finance and may improve your approval odds and terms. We provide a fast, fair trade-in estimate as part of the financing conversation. What used Chevrolet vehicles are available for buyers on a tighter budget? We keep a rotating inventory of used vehicles under $19,995 in addition to our full used and Certified Pre-Owned lineup. Our finance team can help match a vehicle to what you can realistically afford. Start Your Financing Journey Today We're located at 8843 US HWY 441 in Leesburg, FL — just minutes from The Villages. Bad credit doesn't have to keep you from driving home in a Chevy you love. Get Pre-Qualified Check Buying Power Value My Trade Shop Affordable Inventory

Finance specialist reviewing Chevrolet financing options with a customer at Cecil Clark Chevrolet in Leesburg, FL

Chevrolet Financing for Bad Credit and First-Time Buyers in Central Florida

Whether you are dealing with a rough credit history, negative equity on a trade-in, or simply buying your very first vehicle, we understand how stressful the financing process can feel. At Cecil Clark Chevrolet — a family-owned dealership serving Central Florida since 1972 — our job is to make that process as clear and stress-free as possible. We work with buyers at every stage of their financial journey, and we have helped thousands of customers in Leesburg, The Villages, Lady Lake, Eustis, Tavares, and across Lake and Sumter Counties find a path to the Chevrolet they deserve. Can You Finance a Chevrolet with Bad Credit in Central Florida? The short answer is yes — and we mean that sincerely. A low credit score, a past bankruptcy, or a few missed payments do not automatically close the door on driving a new or used Chevrolet. Our finance team works with a broad network of lending partners who specialize in helping buyers with difficult credit histories. These are not lenders who will turn you away at the first sign of trouble — they are partners who understand that life happens and who want to help you get back on track. What sets us apart is that we take a no-pressure approach to every conversation. When you come in — or when you apply online before your visit — we sit down with you, learn about your situation, and map out realistic options that fit your budget. We have been doing this for more than 50 years, and we know that finding the right financing path for someone with challenging credit takes more effort, not less. That is exactly the kind of effort we put in every single day. You are not alone. Many of the Central Florida buyers we work with have faced the same challenges you may be facing right now — and nearly all of them left our lot in a vehicle they love. Start your pre-qualification online and let us show you what is possible. Financing Options for Every Situation No two buyers are in the same position, and we do not treat them as if they were. Here is a look at how we approach the most common financing challenges our customers bring to us. Bad Credit or Rebuilding Credit We work with lenders who say yes when others say no. Whether your score has dropped from medical bills, a job change, or past financial difficulty, we have programs designed to help you finance and rebuild at the same time. Get Pre-Qualified First-Time Buyers No credit history is not the same as bad credit — and we treat it that way. Our team will connect you with lenders experienced in first-time buyer programs and walk you through exactly what to expect every step of the way. Check Your Buying Power Negative Equity / Upside Down If you owe more on your current vehicle than it is worth, we can help you explore your options — including rolling the balance into your new loan or identifying a trade-in value that minimizes the gap. We have a full guide to help you understand the process. Read the Guide No Credit History Recent graduates, new residents, or anyone who has simply never borrowed before — we have seen every scenario. A thin credit file does not have to mean a dead end. We will help you find a lender and a vehicle that makes sense for where you are right now. Value Your Trade Chevrolet Lease Programs Near The Villages and Leesburg Leasing is worth a serious look — especially if lower monthly payments or driving a new model every few years matters to you. When you lease a Chevrolet through us, you are paying for the vehicle's use over the lease term rather than building toward full ownership. That structure typically means a more manageable monthly payment and the flexibility to upgrade when the term ends. Our current Chevrolet lease specials are updated regularly and include a range of models suited to Central Florida drivers — from the Equinox and Trax for daily commuting to the Silverado for those who need capability. For buyers interested in maximizing upfront value, we also offer a one-pay lease option that can reduce the total cost of leasing by paying the full term upfront. GM Rewards Members get more. If you are enrolled in My GM Rewards, your points can be applied toward lease and purchase payments, giving you additional savings on top of any active incentives. Ask our team how to maximize your rewards on your next vehicle. Not sure whether financing or leasing is right for your situation? Our team will walk you through both options side by side — no pressure, just a clear comparison based on your actual driving needs and budget. You can also explore current GM specials and manufacturer incentives to see what programs are available right now. Shopping for a truck? Our guide to getting a Chevy Silverado loan with low APR near The Villages explains how credit tier, loan term and the special-APR-versus-cash-back choice set the rate you actually pay. Protecting Your Investment After Purchase For buyers who are working hard to stay within a tight budget, unexpected costs after purchase can be the difference between a smooth ownership experience and a stressful one. That is why we make sure every buyer understands the protection options available to them — not as upsells, but as real tools that can protect you financially over the life of your vehicle. GAP Coverage If your vehicle is totaled or stolen, GAP coverage bridges the difference between what your insurance pays and what you still owe on the loan — critical for buyers with negative equity or minimal down payments. Pre-Paid Maintenance Lock in your routine service costs at today's prices. Pre-paid maintenance plans cover oil changes, tire rotations, and more — so you are never caught off-guard by a service bill when it is time to come in. Tire & Wheel Protection Central Florida roads can be tough on tires. Our tire and wheel protection plan covers the cost of repair or replacement so a pothole or road hazard does not blow your monthly budget. Vehicle Protection Plans Extended protection beyond the factory warranty gives you peace of mind as your vehicle ages. Ask our finance team about protection plan options that can be rolled into your monthly payment. How to Get Pre-Qualified Before Your Visit One of the best things you can do before coming to see us is get pre-qualified online. It takes just a few minutes, it does not require a hard credit pull at the initial step, and it gives you a real sense of what you can expect before you ever set foot on our lot. Here is how the process works: Submit your pre-qualification online. Visit our pre-qualification page and provide some basic information. This is a soft step designed to give us a starting point — not a commitment from you or us. Check your buying power. Use our buying power tool to understand the range of vehicles within reach given your income and current financial picture. This helps you shop realistically and confidently. Estimate your monthly payment. Our payment calculator lets you input different vehicle prices, down payment amounts, and term lengths to see how your monthly payment shifts. Use it to find a combination that fits your budget before you ever talk numbers in person. Value your trade-in. If you have a vehicle to trade, get a ballpark figure through our trade-in tool before your visit. That number factors into your overall financing picture and can make a real difference — especially if you are working through negative equity. Come see us — or call ahead. Once you have a sense of your numbers, our finance team is ready to take it from there. Walk in during our sales hours (Mon–Thu 8 AM–7 PM, Fri–Sat 8 AM–6 PM), or call us at (352) 702-9073 to get a head start. If you are curious about how recent legislative changes could affect your auto loan interest, check out our post on how the auto loan interest deduction may help Chevy buyers in Central Florida. Why Central Florida Buyers Trust Our Finance Team We have been at this a long time — and the buyers who keep coming back to us, and who send their families and neighbors our way, are the proof. Here is what makes our approach different. Broad Lender Network We work with dozens of lending partners — including lenders who specialize in credit-challenged buyers — so we can find a match even when other dealerships cannot. 50+ Years, Family-Owned Founded in 1972, Cecil Clark Chevrolet has been a trusted name in Lake and Sumter Counties for generations. We are not a franchise — we are a family, and we treat every customer that way. No-Pressure Process We will never rush you into a decision or make you feel judged for your credit situation. Our finance specialists are advisors, not salespeople — their goal is to find something that genuinely works for you. All Credit Situations Welcome Bad credit, no credit, negative equity, first-time buyers — we have seen it all and helped buyers through it all. No situation is too complicated for our team. Online Tools, Anytime Pre-qualify, check your buying power, and estimate your payment from your phone or computer — any time of day. You do not have to wait for business hours to start exploring your options. Transparent Process We explain every number, every term, and every option in plain language. You will never leave our finance office wondering what you signed. Read what our customers say on our reviews page. Frequently Asked Questions Can I buy a Chevrolet with bad credit at Cecil Clark Chevrolet near The Villages? Yes. We work with buyers across the full credit spectrum — including those with past credit challenges, collections, or a bankruptcy. Our finance team works with a wide network of lenders who specialize in credit-challenged situations. We encourage you to apply online before your visit so we can present your options with no pressure. What are my options if I have negative equity on my current vehicle? Negative equity — being upside down — means you owe more than your vehicle is worth. Our team can roll that remaining balance into your new financing, explore trade-in options, or help you find a vehicle and payment structure that makes the transition manageable. Read our full guide on trading in a car with negative equity in Central Florida for a detailed walkthrough. Does Cecil Clark Chevrolet offer special financing programs for first-time car buyers? Yes. We work with lenders that have programs specifically designed for first-time buyers who may have little or no credit history. Our finance team will guide you through the process from start to finish — from pre-qualification to signing — so you know exactly what to expect. Use our buying power tool to get started before your visit. What is the difference between financing and leasing a Chevrolet in Central Florida? When you finance a Chevrolet, you are working toward full ownership through monthly payments. When you lease, you pay for the vehicle's use over a set term and return it — or have the option to buy — at the end. Leasing typically offers lower monthly payments and lets you drive a new model every few years. Our team can compare both options side by side based on your driving habits and budget. See our current Chevrolet lease specials to explore available offers. How do I know if I qualify for Chevrolet financing before visiting the dealership? You can get pre-qualified online in minutes — no hard credit pull required for the initial step. Our online tools also let you check your buying power and run payment estimates so you can shop with confidence. If you have questions before submitting, call us at (352) 702-9073 or visit our dealership page for The Villages area. Ready to Get Behind the Wheel of a Chevrolet? Whatever your credit situation, our finance team at Cecil Clark Chevrolet is here to help. Start online, then come see us in Leesburg — we serve The Villages, Lady Lake, Eustis, Tavares, Mount Dora, and all of Central Florida. Get Pre-Qualified Now Browse New Inventory View Lease Specials Calculate My Payment

Red Chevrolet Equinox RS, the SUV behind this month's Equinox lease deals near Tavares, FL

Current Chevy Equinox Lease Deals Near Tavares, Florida This Month

Chevrolet Equinox lease deals near Tavares reset on the first business day of every month, because GM publishes its lease cash, loyalty rebates and residual values thirty days at a time — so the payment quoted to you today is the one to act on, and it will read differently in October. The live figures always sit on our current Chevrolet lease specials page for Leesburg, and at Cecil Clark Chevrolet, the Chevrolet dealership serving Tavares, FL just up US HWY 441, we will show you what is actually driving that number before you sign anything. Quick answer: what to ask for on an Equinox lease this month Current offer: whatever is posted this cycle — the program turns over monthly. Lowest monthly payment: a longer term with a 10,000-mile allowance. Least cash up front: a zero-due-at-signing lease. Lowest total cost: a one-pay lease. Biggest single lever: GM lease loyalty or conquest cash, if you qualify. See This Month's Chevy Offers What Actually Sets Your Equinox Lease Payment A lease payment is not one number somebody picks — it is four numbers doing math, and only two of them are negotiable. Once you can tell which is which, comparing an Equinox quote from us against one from a store in Mount Dora or Ocala takes about two minutes instead of an afternoon. These are the four inputs behind every figure on the sheet, and the ones worth asking about by name. Capitalized Cost The agreed selling price the lease is written against. This is the negotiable half of the equation, and every dollar taken off it comes straight back out of your monthly payment. Residual Value What GM projects the Equinox will be worth at lease end, set as a percentage of MSRP. You cannot negotiate it, but a strong residual is exactly why some months lease better than others. Money Factor The lease equivalent of an interest rate, quoted as a small decimal. Multiply it by 2,400 for the rough APR. Your credit tier, not your haggling, decides which one you are offered. Term & Mileage Allowance Usually 24, 36 or 39 months set against a yearly mileage cap. A shorter term and a higher cap each raise the payment, so match both to how you genuinely drive. Equinox Lease Offers You'll See Near Tavares This Month Low Payment, Cash Due at Signing The headline deal in most advertising. It assumes a set amount due at signing that usually folds in the first payment, tax, tag and fees. Always ask what that due-at-signing figure is before you compare it against anything else. See 2026 Chevrolet Equinox specs and trims. Zero Due at Signing Everything rolls into the monthly instead. The payment runs higher, but you keep your cash — which matters when insurance, tag transfer and the first payment all land in the same week. One-Pay Lease — Lowest Total Cost You settle the whole lease up front and GM cuts the money factor sharply in return, so the total outlay is the lowest of any structure. Worth pricing if you have cash sitting idle. Here is how a one-pay Chevrolet lease works. Loyalty, Conquest and Program Cash GM lease loyalty, conquest cash for current non-GM owners, and the military, first-responder, educator and supplier programs stack on top of the advertised offer more often than shoppers expect. Ask about every one you might qualify for. Lease Pull-Ahead If your current lease is within a few payments of maturity, GM will sometimes waive the remainder to move you into a new Equinox early. Ask before you assume you are locked in until the end of your term. Browse New Equinox Inventory Estimate Your Payment Choosing a Term and Mileage That Fits Tavares Driving Most Tavares drivers are not stacking highway miles — a run down Burleigh Boulevard, a trip up 441 into Leesburg, the occasional Turnpike drive to Orlando. That pattern usually fits a 10,000-mile-a-year allowance, which prices lower than the standard cap. The FTC points out that most standard leases cap you at 15,000 miles a year or less, that you are responsible for excess wear and damage, and that ending a lease early can bring a substantial termination charge — so pick your number honestly rather than optimistically, because buying extra miles when you sign costs less than the per-mile overage at turn-in. On the vehicle side, leasing keeps you in a current-generation Equinox: the IIHS crash-test ratings rate the 2026 model Good for moderate overlap front, side impact and headlights, with Acceptable results in the tougher small overlap front test. Credit Tiers and Getting Approved Before the Month Turns Lease approvals run on credit tiers, and the tier you land in moves your money factor further than any negotiating will. A thin or bruised credit file does not rule out a lease — it just means knowing where you stand before you start shopping. Our guide to Chevrolet financing for first-time buyers and credit-challenged shoppers in Central Florida covers the full picture, and if a loan turns out to suit you better than a lease, our walkthrough of getting approved for a Chevrolet auto loan with bad credit in Leesburg takes that side apart. Either way, get pre-qualified before the calendar flips: an offer you qualify for on the 28th may not exist on the 2nd. Serving lease customers across Lake County We write and service Chevrolet leases for drivers in Tavares, Mount Dora, Eustis, Leesburg, Lady Lake and The Villages, and most of the paperwork can be handled before you ever come in. Ask about free local delivery if you would rather have the Equinox brought to your driveway. Get Pre-Qualified Value Your Trade Frequently Asked Questions What are the current Chevy Equinox lease deals near Tavares, Florida this month? Chevrolet lease programs reset on the first business day of each month, so the current Equinox offer near Tavares is whatever GM has published for this cycle — typically a low monthly payment with cash due at signing, plus lease cash and loyalty rebates for those who qualify. Because the figures change every 30 days, check our posted lease specials or call 352-702-9073 rather than relying on an older quote. How much should I put down on a Chevy Equinox lease? As little as the deal allows. A lease down payment, called a capitalized cost reduction, lowers your monthly figure but is not refunded if the vehicle is totaled or stolen early in the term. Many Tavares shoppers put down only the first payment, tax, tag and fees, then let the monthly carry the rest. Ask for both a zero-due-at-signing quote and a cash-down quote, and compare the totals. What mileage allowance should I choose on a lease in Lake County? Look at your last twelve months first. If your driving is mostly Tavares to Leesburg, Mount Dora and Eustis, a 10,000-mile-a-year allowance usually prices lowest and still leaves room. Choose 12,000 or 15,000 if you commute to Orlando or take regular trips out of state. Buying extra miles when you sign costs less than paying the per-mile overage charge at turn-in. Can I lease a Chevy Equinox with less-than-perfect credit? Often, yes. Lease approvals run on credit tiers, and a lower tier usually means a higher money factor rather than an automatic decline. A trade with equity, a co-signer or a larger amount due at signing can all help. Get pre-qualified before you shop so you know which tier you land in, and ask us to price a finance option alongside the lease. Is it better to lease or buy a Chevrolet Equinox in 2026? Lease if you drive under about 12,000 miles a year, want a lower monthly payment and like a new vehicle every three years. Buy if you keep vehicles a long time, drive heavy miles or want to own an asset at the end. Ask for both numbers on the same Equinox — total cost over the term tells you more than the monthly payment alone. See This Month's Equinox Lease Deals Near Tavares Tell us how many miles you drive and how long you want the vehicle, and we will price the monthly lease, the one-pay and the finance option side by side. Family-owned on US HWY 441 in Leesburg since 1972 — a short drive up from downtown Tavares. Schedule a Test Drive Check Your Buying Power Browse New SUVs Read Customer Reviews